
What Happens When Your Health Insurance Claim Gets Denied — And How to Appeal It
Insurance Writer
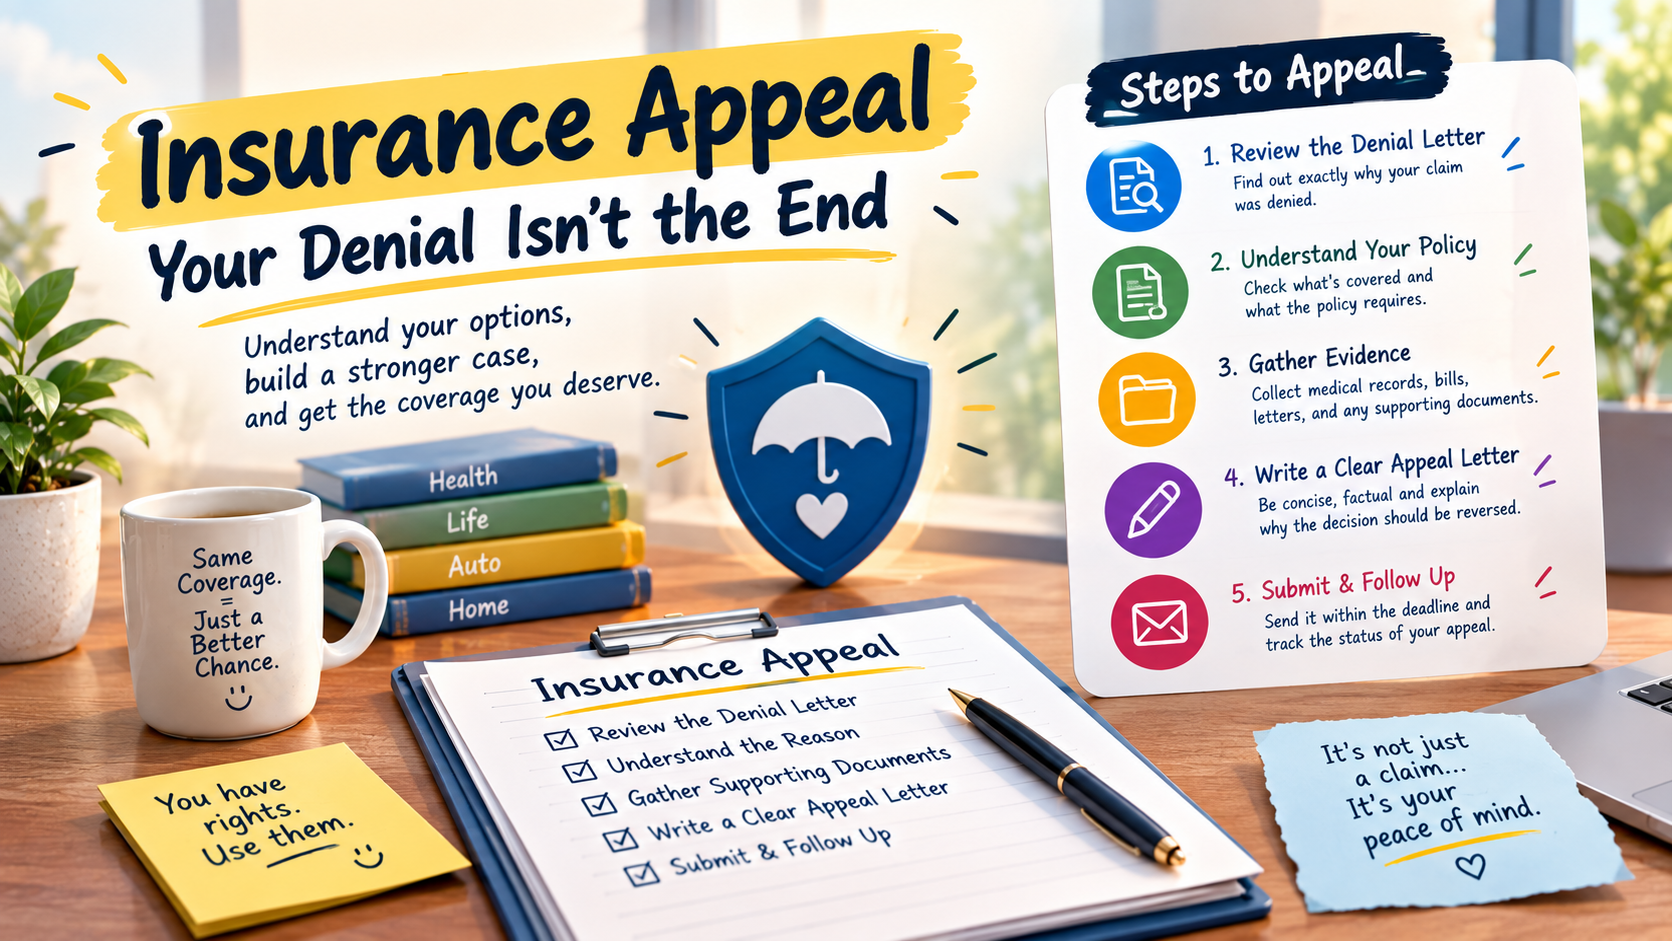
Getting a health insurance claim denied can feel final, but it usually isn't. Most denials fall into a handful of common categories, and most insurers are required to offer a structured appeals process with real deadlines. Understanding why claims get denied — and exactly how to push back — can be the difference between eating a large bill and getting it reversed.
Why Claims Actually Get Denied
| Reason | What It Means |
|---|---|
| Missing or incorrect information | A billing code error, missing member ID, or mismatched patient details on the claim |
| Not medically necessary | The insurer's review determined the service didn't meet its criteria for necessity — a common but often appealable reason |
| Out-of-network provider | The provider wasn't in your plan's network, and no emergency or No Surprises Act protection applied |
| Prior authorization not obtained | Some procedures require insurer approval before the service — skipping this step can trigger an automatic denial |
| Coverage exclusion | The specific service isn't covered under your plan at all, regardless of documentation |
The first four categories are often reversible through an appeal, especially when the root cause is a documentation error rather than an actual exclusion. A true coverage exclusion is harder to overturn, though it's still worth confirming the denial reason is accurate before accepting it.
Step 1: Read the Denial Reason Carefully
Your Explanation of Benefits will include a remark code explaining the denial. Insurers are required to provide this reason, and it's usually decoded in a key at the bottom of the EOB or in a separate denial letter. Understanding the specific reason — rather than just "it was denied" — determines what kind of appeal you need to file.
Step 2: Gather Supporting Documentation
Depending on the denial reason, this might include medical records showing necessity, a letter from your doctor supporting the treatment, the itemized bill, or proof that a prior authorization was in fact obtained. The more directly your documentation addresses the specific denial reason, the stronger the appeal.
Step 3: File an Internal Appeal
Every insurer has a formal internal appeals process, typically with a window of around 180 days from the denial date. This usually involves submitting a written appeal along with your supporting documentation, and the insurer is required to review it and respond within a set timeframe — often 30 to 60 days, faster for urgent medical situations.
Step 4: Request an External Review If the Internal Appeal Fails
If the internal appeal is denied, most plans are required to offer an external review by an independent third party not affiliated with the insurer. This is often your best shot at a fair reassessment, since the reviewer has no financial stake in the outcome. External review requests typically need to be filed within about four months of the final internal denial.
Worked Example: Reversing a "Not Medically Necessary" Denial
Say a claim for an MRI is denied as "not medically necessary." The first step is requesting the specific clinical criteria the insurer used to make that determination — insurers are generally required to disclose this on request. If your doctor's notes support the medical necessity of the scan (for example, documenting symptoms or a prior treatment that didn't resolve the issue), submitting a letter from your doctor along with the relevant clinical notes as part of an internal appeal is often enough to reverse this type of denial, since it's frequently a documentation gap rather than a genuine exclusion.
When to Escalate Beyond the Insurer
If both the internal appeal and external review are unsuccessful, or if you believe the insurer is acting in bad faith, your state's insurance department can often investigate complaints against insurers operating in that state. This is a separate channel from the insurer's own appeals process and can apply additional pressure, particularly in clear-cut cases of improper denial.
Common Mistakes
1. Not reading the specific denial reason before appealing. A generic appeal that doesn't address the actual remark code is far less likely to succeed than one targeted at the specific issue.
2. Missing the internal appeal deadline. The roughly 180-day window is firm — appealing after it closes can mean losing the right to challenge the denial at all.
3. Assuming "not medically necessary" denials can't be reversed. This is one of the more commonly overturned denial types when supported with the right clinical documentation.
4. Not requesting the insurer's specific review criteria. Insurers are generally required to disclose the clinical guidelines used for a denial on request — this makes it much easier to build a targeted appeal.
5. Giving up after the internal appeal. An external, independent review is often the fairest step in the process and shouldn't be skipped if the internal appeal fails.
Key Takeaway: Most claim denials fall into a small number of common, often-reversible categories — read the specific reason, gather targeted documentation, and use both the internal appeal and external review before assuming the denial is final.
Frequently Asked Questions
How long do I have to appeal a denied claim?
Most insurers set an internal appeal deadline around 180 days from the denial date, though it's worth confirming your specific plan's timeline in the denial letter or EOB.
What is an external review, and is it different from the insurer's appeal?
Yes — an external review is conducted by an independent third party not affiliated with your insurer, used after an internal appeal is denied, and is generally a required option under most plans.
Can a "not medically necessary" denial actually be reversed?
Often, yes — especially when supported by a doctor's letter and clinical notes addressing the specific criteria the insurer used to deny the claim.