
The 4% Rule: How Much Money You Actually Need to Retire
Retirement Writer
What Is the 4% Rule?
The 4% rule is a widely referenced retirement planning guideline that suggests you can withdraw 4% of your retirement portfolio in your first year of retirement, then adjust that dollar amount for inflation each year after, with a reasonably low risk of running out of money over a 30-year retirement. It comes from historical research analyzing market returns and withdrawal rates (commonly known as the "Trinity Study").
How to Use It to Calculate Your Retirement Number
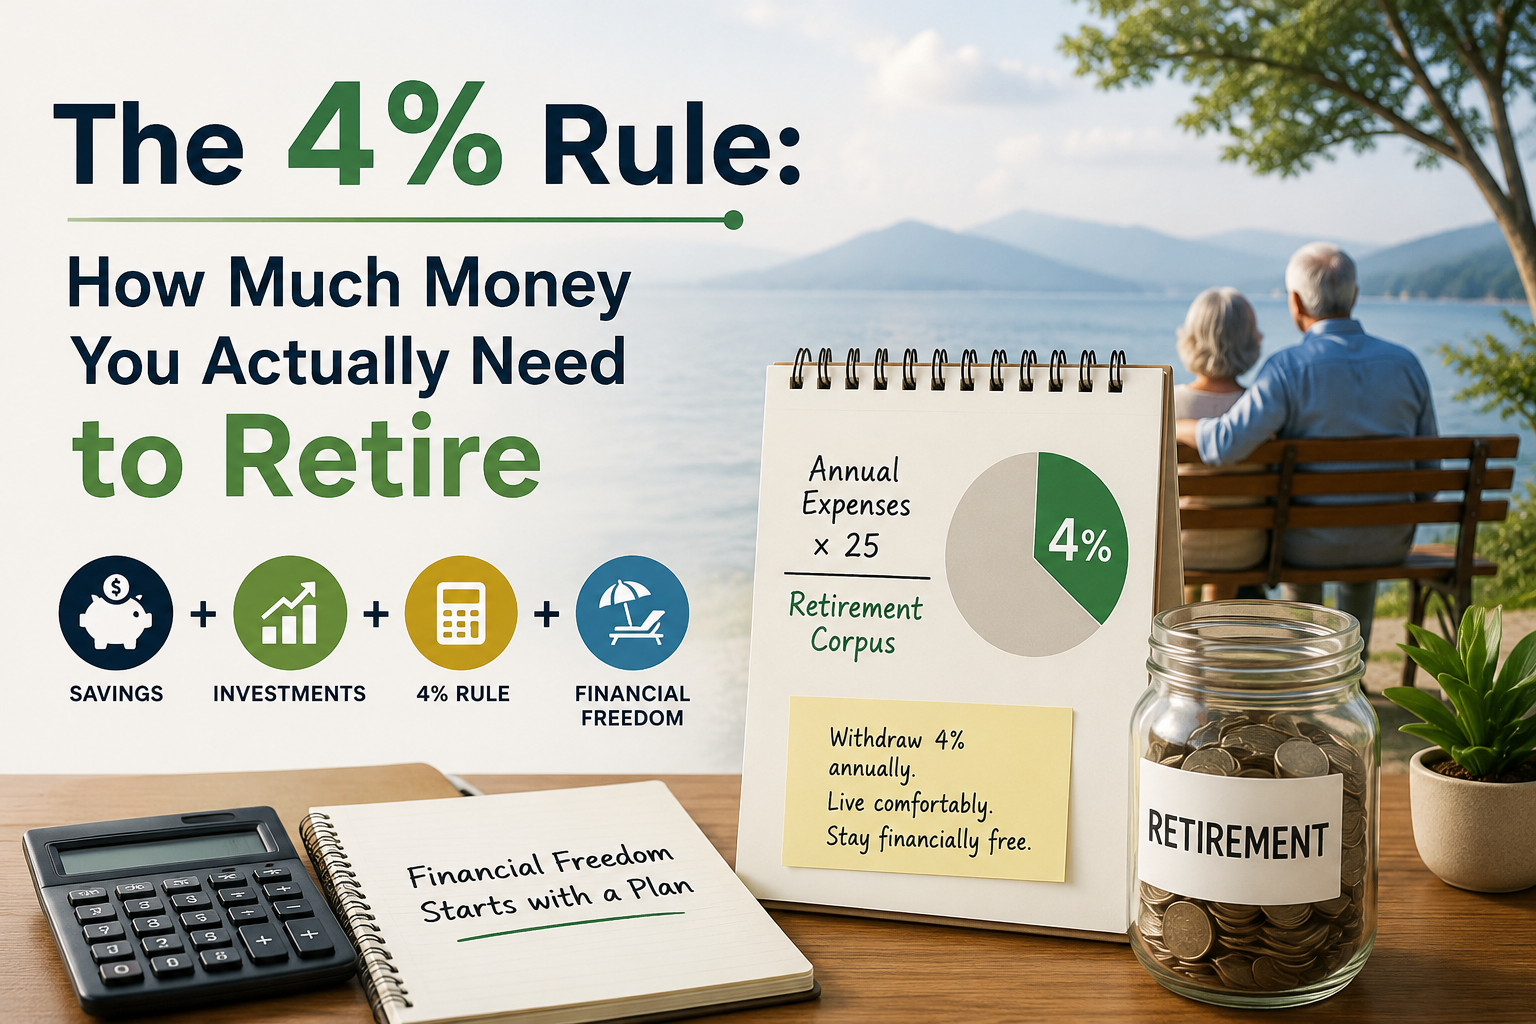
Flip the 4% rule around, and it tells you how large a portfolio you need: divide your desired annual retirement spending by 4% (or equivalently, multiply by 25). If you want $60,000 per year in retirement income, you'd need roughly $1.5 million invested ($60,000 ÷ 0.04 = $1,500,000).
A Worked Example
| Desired Annual Spending | Retirement Portfolio Needed (25x) |
|---|---|
| $40,000 | $1,000,000 |
| $60,000 | $1,500,000 |
| $80,000 | $2,000,000 |
| $100,000 | $2,500,000 |
Note this calculation is for spending covered entirely by your portfolio — if you'll also have Social Security or a pension, subtract that expected income first, then apply the 25x multiple to the remaining gap.
Why It Works (and Its Limitations)
The 4% figure comes from historical backtesting across many decades and market conditions, designed to survive even relatively poor sequences of returns early in retirement. However, it's not a guarantee — it's a probabilistic guideline based on past market history, and future returns, inflation, and your actual retirement length could all differ from the historical periods studied. Many planners today treat 4% as a reasonable starting point rather than an exact, risk-free number.
Factors That Can Push Your Safe Withdrawal Rate Higher or Lower
- Retirement length: A 40-year retirement (early retirees) may need a more conservative rate, like 3.5%, while a shorter retirement window could support a higher rate
- Flexibility in spending: If you can cut back during down markets, a rigid 4% (adjusted only for inflation) may be overly conservative
- Portfolio composition: The original research assumed a specific stock/bond mix — a portfolio significantly more conservative or aggressive may not follow the same safe withdrawal math
- Fees: High investment or advisory fees eat into your effective withdrawal capacity — the 4% rule assumes a reasonably low-cost portfolio
Common Mistakes to Avoid
1. Treating 4% as a guaranteed, risk-free number. It's a historically-derived guideline with a strong track record, not a mathematical certainty — building in some flexibility (adjusting spending in bad years) improves your actual safety margin.
2. Forgetting to subtract other guaranteed income first. The 25x multiple applies to the portion of spending your portfolio needs to cover — Social Security, pensions, or rental income should be subtracted from total spending before calculating your target number.
3. Ignoring healthcare costs, especially before Medicare eligibility. Early retirees covering their own health insurance before age 65 often underestimate this specific expense category when calculating total retirement spending needs.
4. Not adjusting for a longer-than-average retirement. Early retirees planning for a 40+ year retirement horizon should generally use a more conservative withdrawal rate than someone retiring at a traditional age with a shorter time horizon.
5. Applying the rule rigidly without accounting for market conditions. Some retirees successfully use "dynamic" withdrawal strategies — spending a bit less in down markets and more in strong years — rather than a fixed inflation-adjusted amount regardless of portfolio performance.
Key Takeaway: The 4% rule gives you a quick, historically-grounded way to estimate your retirement number — roughly 25 times your annual spending need, after subtracting other guaranteed income. It's a useful starting point for planning, not an exact guarantee, and building in some spending flexibility improves your real-world safety margin.
Frequently Asked Questions
Is the 4% rule still considered reliable today?
It remains a widely used starting point, though many planners now suggest more conservative rates (3-3.5%) for longer retirements or more cautious planning, given uncertainty about future market returns.
Does the 4% rule account for Social Security?
No — the 25x multiple applies specifically to the spending your investment portfolio needs to cover. Subtract expected Social Security or pension income from your total spending target before applying the rule.
What if I plan to retire early, before 65?
A longer retirement horizon generally calls for a more conservative withdrawal rate than the standard 4%, since your portfolio needs to last longer. Many early retirees plan around 3-3.5% instead.
Should my withdrawal amount stay exactly the same every year?
The traditional 4% rule adjusts the dollar amount for inflation each year, but some retirees use more flexible strategies — spending less during market downturns and more during strong years — to reduce the risk of depleting savings.
Does the 4% rule apply to any type of investment portfolio?
The original research was based on a specific mix of stocks and bonds. A portfolio that's significantly more conservative (mostly cash) or aggressive may not follow the same safe withdrawal math, so it's worth considering your actual asset allocation.