
Atal Pension Yojana: Guaranteed Retirement Income for the Unorganised Sector
Retirement Writer
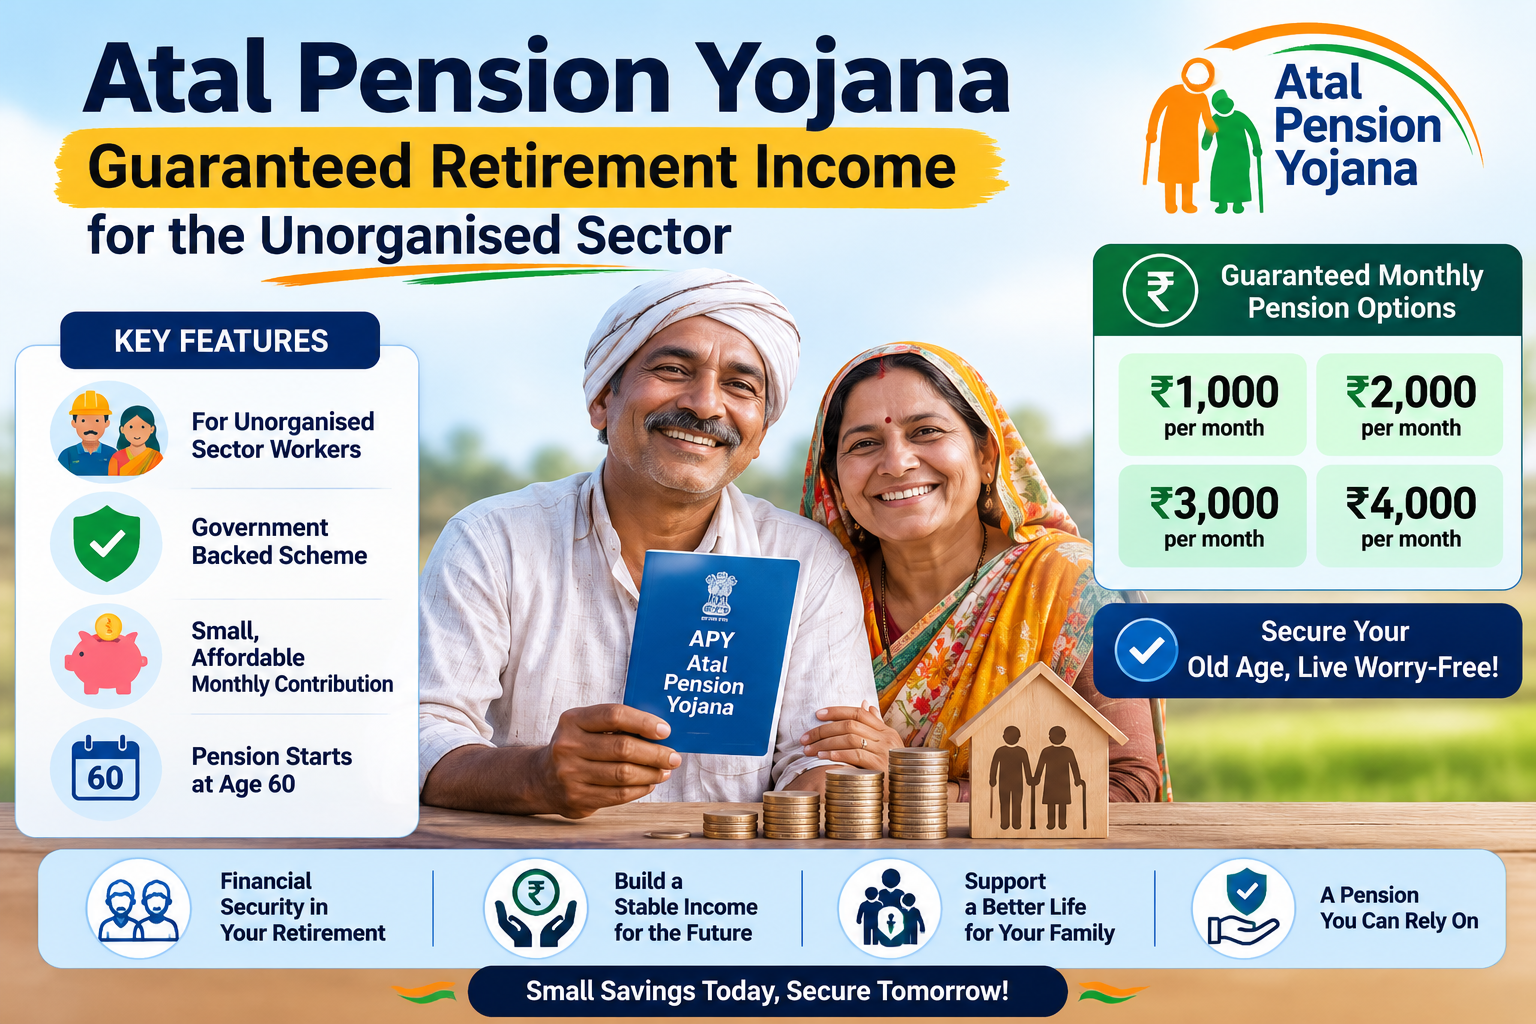
What Is Atal Pension Yojana?
Atal Pension Yojana (APY) is a government-backed pension scheme, launched in 2015-16 and regulated by the PFRDA, designed primarily for workers in the unorganised sector — people who don't have access to an employer-provided pension like EPF. You contribute a small, fixed amount regularly until age 60, and from then on, the government guarantees a fixed monthly pension for life.
Eligibility
- Indian citizen, aged 18 to 40 years at the time of joining
- Must have an active savings bank account or post office savings account, linked to Aadhaar
- Must contribute for a minimum of 20 years, which is why 40 is the upper joining age (to still reach 60 with 20 years of contributions)
- Since October 1, 2022, anyone who is or has ever been an income-tax payer cannot enrol — this is one of the most commonly missed rules
Pension Slabs and How Contributions Work
You choose a guaranteed monthly pension amount — ₹1,000, ₹2,000, ₹3,000, ₹4,000, or ₹5,000 — and your monthly contribution is calculated based on your entry age and the pension slab you pick. The younger you join, the smaller your monthly contribution, since you have longer to contribute. For example, joining at 18 for a ₹1,000 monthly pension requires a contribution as low as ₹42/month; joining later or choosing a higher pension slab increases the monthly amount significantly.
| Feature | Detail |
|---|---|
| Pension amount | ₹1,000 to ₹5,000/month, your choice |
| Contribution frequency | Monthly, quarterly, or half-yearly (auto-debit) |
| Minimum contribution period | 20 years |
| Pension starts | From age 60 |
| Spouse benefit | Same pension amount continues to spouse after subscriber's death |
| Nominee benefit | Accumulated corpus returned to nominee after both subscriber and spouse pass away |
Why the Guarantee Matters
Unlike a market-linked investment such as a mutual fund SIP, APY's pension amount is fixed and guaranteed by the government regardless of how the underlying investments perform. This makes it fundamentally different from NPS or equity-based retirement planning — it trades away higher potential returns for certainty, which is exactly the point for workers who can't afford market risk on their primary retirement income.
Who Should Consider APY?
- Workers in the unorganised sector — daily wage earners, gig workers, domestic workers, small vendors — who have no employer pension coverage
- Anyone who wants a small, guaranteed, low-risk pension as a supplement to other retirement savings, not a replacement for it
- Younger individuals (ideally in their 20s) who can lock in a low monthly contribution for a higher eventual pension
Common Mistakes to Avoid
1. Not knowing about the income-tax payer exclusion. Since October 2022, being (or having been) an income-tax payer disqualifies you from enrolling — many people miss this rule and apply anyway, only to face issues later.
2. Joining too late and getting a high monthly contribution. Waiting until your mid-30s to join significantly raises your required monthly contribution for the same pension amount compared to joining at 18-25 — enrol as early as possible if APY fits your situation.
3. Missing contributions and letting the account lapse. APY has specific rules around penalty charges for delayed contributions, and prolonged non-payment can lead to account closure — keeping sufficient balance for auto-debit is important.
4. Treating APY as your only retirement plan. Even the maximum ₹5,000 monthly pension is unlikely to be enough on its own for a comfortable retirement — APY works best as one part of a broader retirement plan, alongside EPF, PPF, or NPS.
5. Not updating nominee details. Since the scheme has both a spousal continuation benefit and a nominee corpus return, keeping nominee and spouse details accurate and updated ensures the intended person actually receives the benefit.
Key Takeaway: Atal Pension Yojana offers a rare thing in retirement planning — a government-guaranteed, fixed pension regardless of market performance — making it especially valuable for unorganised sector workers with no other pension coverage. Join as early as possible to lock in the lowest contribution for your chosen pension amount, and treat it as one layer of retirement income, not the whole plan.
Frequently Asked Questions
Can income-tax payers join Atal Pension Yojana?
No — since October 1, 2022, anyone who is or has ever been an income-tax payer is no longer eligible to enrol in APY.
What happens to my APY pension if I die before 60?
Your spouse can either continue the contributions and receive the same pension from age 60, or receive the accumulated corpus as a lump sum, depending on the specific rules at the time.
Can I increase or decrease my pension amount later?
Yes — APY allows you to adjust your chosen pension slab (and therefore your contribution amount) once a year, typically in April, to match your changing financial situation.
Is the maximum age to join APY really 40?
Yes — since the scheme requires a minimum 20-year contribution period and pension starts at 60, the latest you can join is age 40.
Is APY only for unorganised sector workers?
It's primarily designed for that group, but any Indian citizen aged 18-40 with a savings account, who isn't an income-tax payer, can technically join — including private sector employees without employer pension coverage.