
How Your CIBIL Score Actually Works and How the Score Is Actually Calculated
Banking Writer
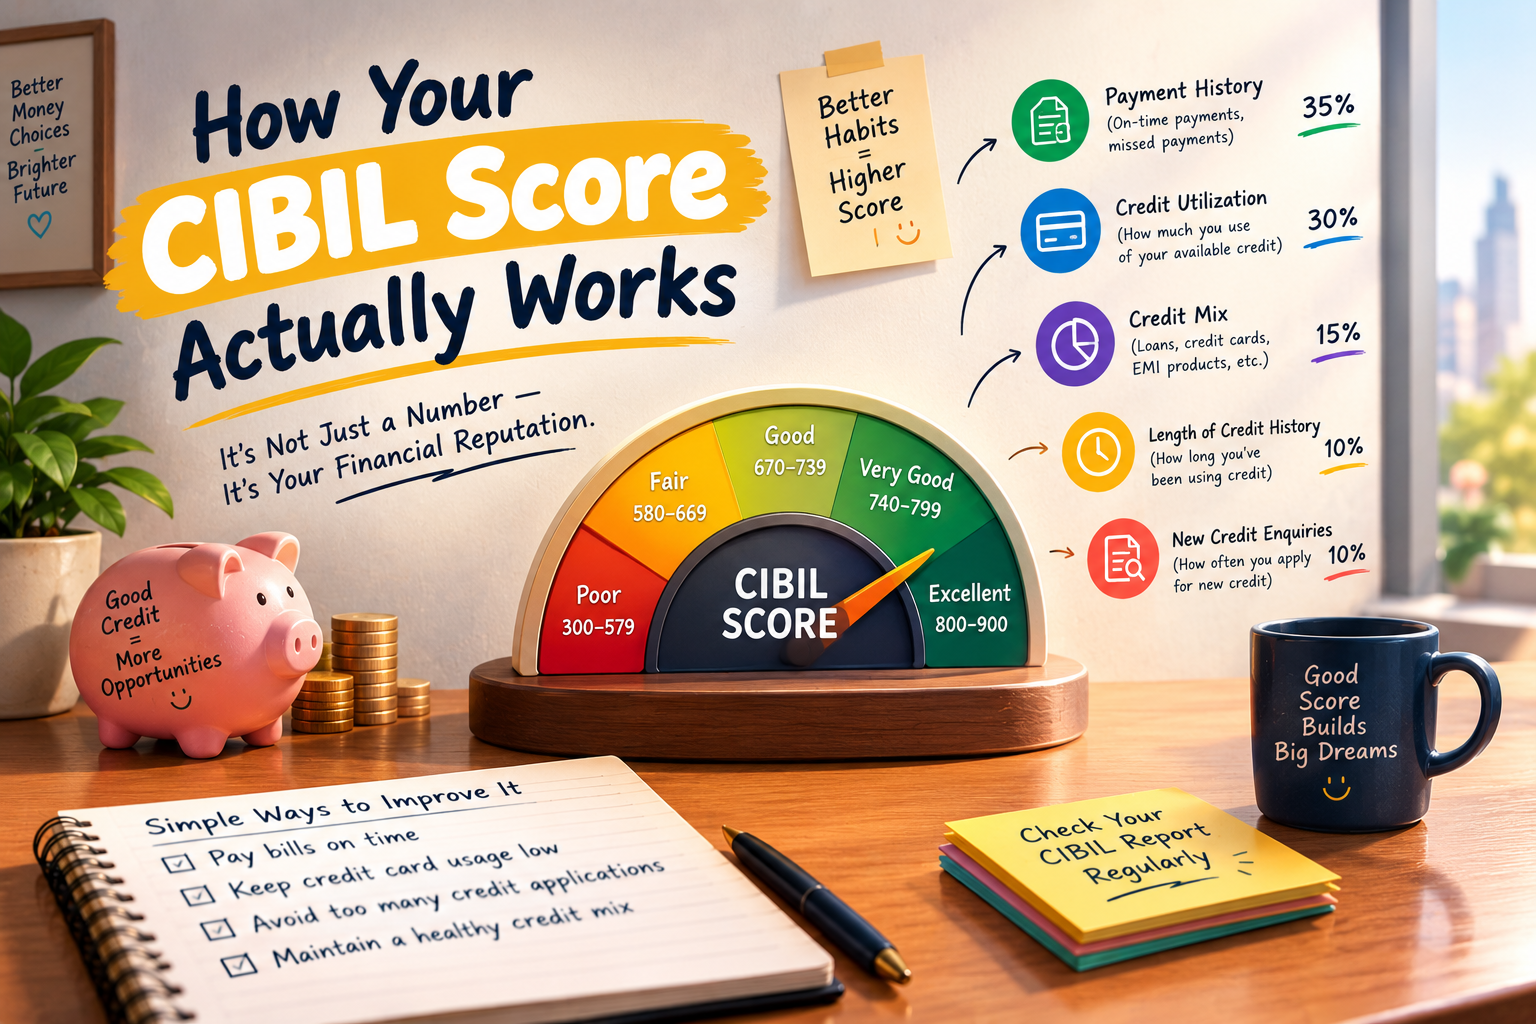
Why Your CIBIL Score Deserves More Than a Quick Glance
Most people only think about their credit score right before applying for a loan or card — by which point it's too late to fix anything that's dragging it down. A CIBIL score isn't one single measurement; it's a rolling summary of how you've handled credit, recalculated every reporting cycle from a handful of specific factors. This guide walks through what the score actually represents, exactly how it's calculated, and how to check it without hurting it — the foundation everything else in this series builds on.
What a CIBIL Score Actually Is, and Why It Follows You Everywhere
A CIBIL score is a three-digit number, ranging from 300 to 900, generated by TransUnion CIBIL from your credit history — every card, loan, and repayment reported by lenders across the country. It isn't just a number banks glance at once; it directly affects loan approval odds, the interest rate you're offered, and even non-lending decisions like rental applications or certain job checks. A higher score doesn't just make approval more likely — it can meaningfully lower the interest rate you're offered on the same loan.
The full breakdown of the score range, what counts as "good," and why it matters even if you're not borrowing right now, is in What Is a CIBIL Score and Why It Matters.
How the Score Is Actually Calculated
The score isn't a mystery formula — it's built from five specific factors, weighted very differently. Payment history and credit utilization together account for the majority of the score, while credit age, credit mix, and recent inquiries fill in the rest. Understanding this weighting is the difference between guessing at what might help your score and actually knowing where to focus.
Factor | What It Reflects |
|---|---|
Payment History | Whether you've paid on time, every time |
Credit Utilization | How much of your available credit you're currently using |
Credit Age | How long your credit accounts have been open |
Credit Mix | Balance between revolving credit (cards) and installment credit (loans) |
Recent Inquiries | How often you've recently applied for new credit |
A full explanation of each factor, and roughly how much weight each carries, is in How Credit Score Is Calculated.
Checking Your Score Without Hurting It
A common myth stops people from checking their own score regularly — the fear that checking it will lower it. In reality, checking your own score is a soft inquiry and has zero impact, no matter how often you do it. Every Indian is also entitled to one free full credit report per bureau per year, directly from the bureau's own website — no need to rely solely on third-party apps that only show a partial picture.
Where exactly to get your free report, how often you should check it, and what to actually look for once you have it, is covered in How to Check Your Free Credit Report.
How These Three Pieces Fit Together
Topic | What It Answers |
|---|---|
What Is a CIBIL Score | What the number means and why it matters beyond just loan approval |
How It's Calculated | Which specific behaviors move the score, and by how much |
Checking Your Free Report | How to monitor your score safely and know exactly what's being reported |
Key Takeaway: Your CIBIL score is a live reflection of five specific, knowable factors — not a black box. Once you understand what's being measured and how to check it safely, you're in a position to actually manage it instead of just reacting to it. The next part of this series covers the everyday credit card habits — good and bad — that move this score the most.
Frequently Asked Questions
What is considered a "good" CIBIL score?
Generally, a score of 750 and above is considered good to excellent by most lenders, though approval thresholds and the interest rates offered can vary by lender and loan type.
How often is my CIBIL score updated?
Lenders typically report account data monthly, so your score generally updates on a similar monthly cycle as new information comes in from your banks and card issuers.
Is CIBIL the only credit bureau in India?
No, India has four licensed credit bureaus — TransUnion CIBIL, Equifax, Experian, and CRIF High Mark — though CIBIL is the most commonly referenced by lenders and borrowers alike.
Does checking my own score through an app count against me?
No — checking your own score, whether directly through the bureau or via an app, is a soft inquiry and has no effect on your score, regardless of how frequently you check it.